All Categories
Featured
Top Methods for Comparing Individual Health Insurance Quotes
Evaluating 2026 Medicare Advantage vs Medicare Supplement...


Affordable Term Life Insurance Quotes Online
Table of Contents
As quickly as the first premium is paid, the entire survivor benefit is set aside for your household. Earnings tax-free death benefit: The death advantage of a life insurance coverage policy is not usually subject to federal earnings taxes. Tax-deferred growth: The development of cash worth inside of whole life insurance is tax-deferred while the funds stay in the policy.
This indicates withdrawals to the degree of expense basis are thought about an income tax-free return of cost basis. Tax-favorable access to money worth loans for any reason: During the insured's life, money value loans taken against an entire life policy are not considered to be a taxable event, although the policy might have a large gain in excess of premiums paid.
Self-funding: The policy can spend for itself with time by using dividends to pay premiums, which contributes to the policy's cost savings part. Special needs defense: A whole life policy can continue to be funded even if you are handicapped. When you elect the Waiver of Premium rider9, if you suffer a qualifying special needs, your policy will continue to offer death benefit security, have cash worth development, and pay dividends even while you aren't paying premiums.

10Distribution: If correctly performed, life insurance coverage assists prevent probate and can provide recipients with greater privacy than might be paid for by a will; a will becomes public as soon as probated, whereas survivor benefit circulations are normally personal, contractually driven deals. Once a policy loan has actually been taken, the yearly dividend can be used to assist repay the policy loan.
Features, arrangements, and costs vary from one insurer to the next, and each entire life agreement is special to the insurance policy holder. Whole life insurance coverage rates depend on aspects such as age, health, and protection quantity, so it is essential to think about these when assessing policies. Typically speaking, there are two standard types of payment structures for entire life: Level premium entire life: This is the most common kind of whole life insurance.
Evaluating Medicare Advantage Coverage Choices
Restricted payment entire life: This kind of policy has a set level premium like a level premium whole life policy, however the premium is just payable for a set duration of time. The advantage is that they are guaranteed to be paid up at the end of the payment duration, so no payment is needed at later ages.
Their accessibility and cost depends upon the policy and the insurance provider. In addition to the Waiver of Premium rider pointed out above, some other options used by Guardian include: Paid-Up Additions Rider: The PUA rider can assist increase the accumulation of tax-deferred cash worths and death advantage. The greater the premium paid into the rider, the higher the protection paid for by the policy.
It provides you a special chance for index-linked upside capacity and the flooring makes sure that your year-to-year downside market exposure is limited. Accidental Death Benefit: Offers an extra survivor benefit if death happens by accidental physical injury. Accelerated Benefit Rider: Provides accelerated benefits, enabling you to access a part of the death benefit early if you are detected with a chronic or terminal illness.
Understanding Whole Life Insurance Functions
Guaranteed Insurability Alternative (GIO): Offers the policy owner the right to acquire additional insurance without evidence of insurability. The GIO can end up being much more valuable in case of special needs: A guaranteed who is disabled and has their premium waived may work out the GIO rider, and Guardian will pay the premium on the new policy An entire life insurance policy is among the most essential monetary purchases you can make.
12 Comparing life insurance business and their life insurance offerings such as whole life, universal life, fixed premiums, ensured death advantages, and money value growth is vital to discovering the best policy for your requirements.
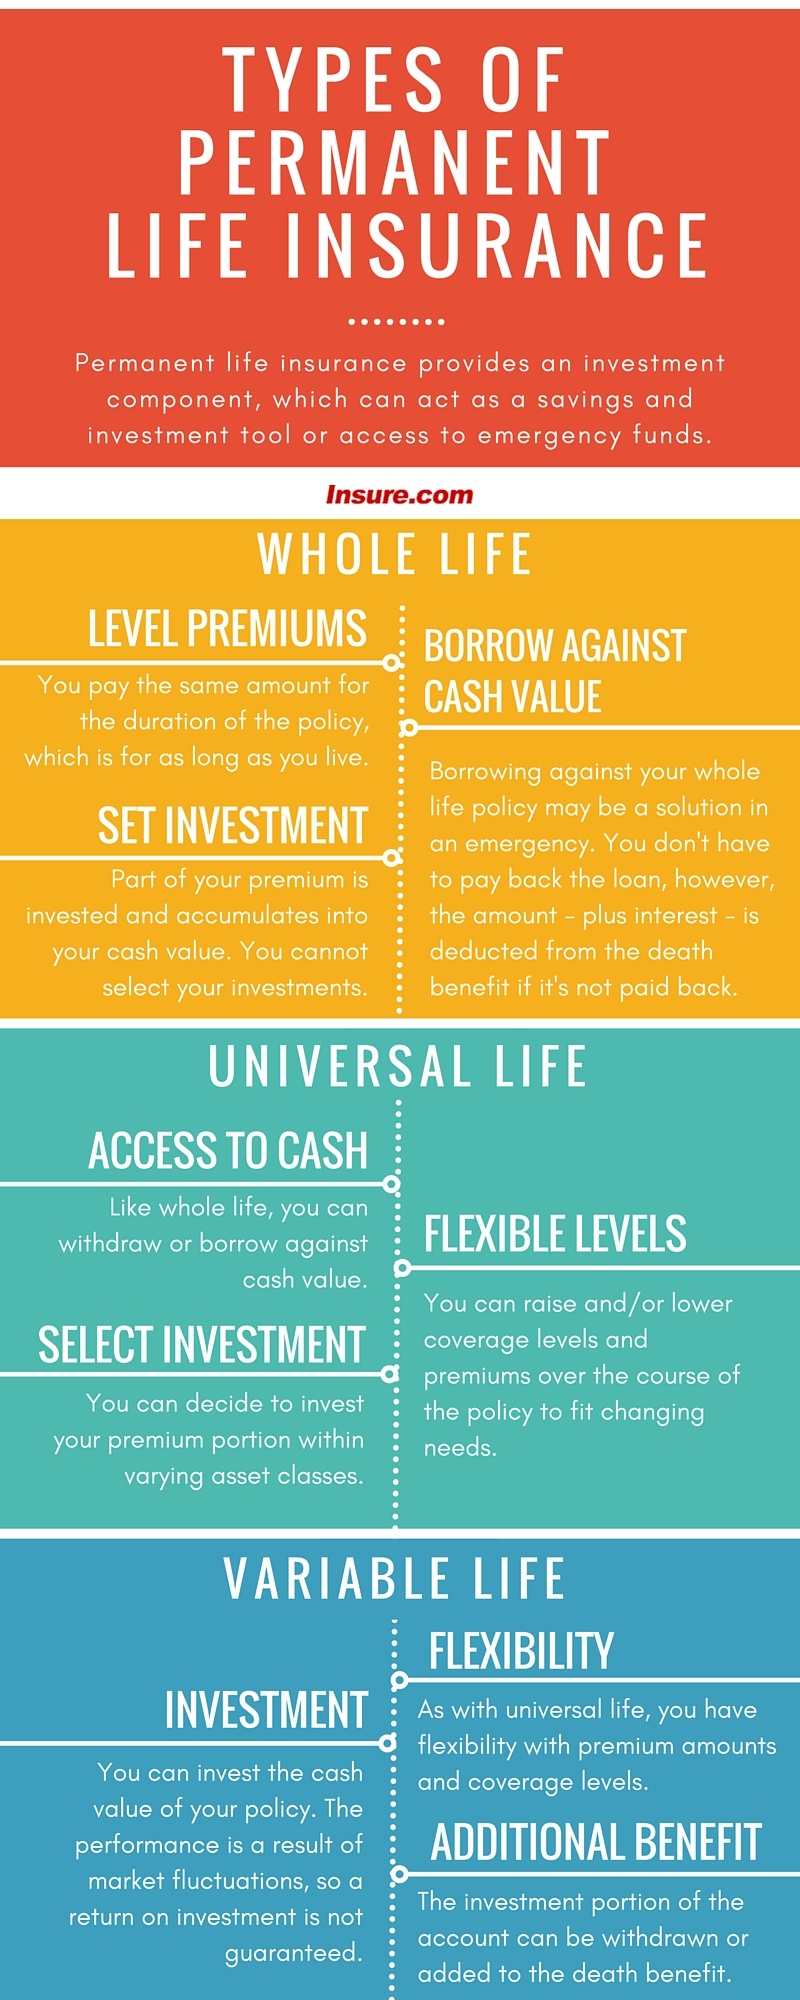
Discuss your situation with an insurance coverage expert or financial specialist who understands entire life insurance and can guide you to the option that finest meets your requirements. If you do not know such an expert, ask a buddy or colleague for a recommendation.
An entire life policy has cash value that grows with time. You can cash it out to help supplement retirement, or obtain against it at any time, for any factor. Entire life policies have an element described as the policy's money value: A part of your premium dollars can grow gradually on a tax-deferred basis, so you do not pay taxes on the gains.

Latest Posts

Top Methods for Comparing Individual Health Insurance Quotes

Evaluating HMO vs PPO Health Coverage

Evaluating 2026 Medicare Advantage vs Medicare Supplement Plans